Monthly Portfolio Update: October 2026
This is my October 2026 update on the income portfolio. Each month I set out the holdings at cost, the distributions the portfolio received, the changes I made and the news from the holdings.
Portfolio goal
The portfolio is built to pay a monthly income that grows over time. Distributions are not drawn down: I reinvest them manually rather than through dividend reinvestment plans, adding to holdings when prices are weak.
Income comes from two components, listed investment companies paying franked dividends and listed credit trusts paying monthly distributions. Starting October a small growth component sits alongside them.
Portfolio summary
Holdings at cost on 31 October, with the change in cost during the month in brackets.
| Holding | Cost base, 31 Oct (change) | Weight | Yield on cost |
|---|---|---|---|
| WHI Whitefield Income | $197,550 (+$23,237) | 28.20% | 7.59% |
| GCI Gryphon Capital Income Trust | $181,702 (+$35,584) | 25.94% | 8.15% |
| MXT Metrics Master Income Trust | $95,910 (no change) | 13.69% | 9.13% |
| TCF 360 Capital Mortgage REIT | $51,682 (+$10,267) | 7.38% | 11.20% |
| PL8 Plato Income Maximiser | $41,970 (no change) | 5.99% | 6.74% |
| QRI Qualitas Real Estate Income Fund | $32,453 (no change) | 4.63% | 8.18% |
| KKC KKR Credit Income Fund | $29,165 (−$18,122) | 4.16% | 9.47% |
| WMX WAM Income Maximiser | $26,870 (no change) | 3.84% | 6.74% |
| MA1 MA Credit Income Trust | $23,947 (no change) | 3.42% | 9.65% |
| LEND VanEck Global Listed Private Credit (AUD Hedged) ETF | $14,798 (no change) | 2.11% | 10.95% |
| GHHF Betashares Wealth Builder Diversified All Growth Geared (30-40% LVR) Complex ETF | $4,435 (new) | 0.63% | 2.32%* |
| Income portfolio (excluding GHHF) | $696,048 (+$50,966) | 99.37% | 8.38% |
| Total portfolio | $700,483 (+$55,401) | 100% | 8.34% |
Weight is each holding’s share of the total cost base. Yield on cost uses each holding’s October rate on 31 October units, grossed up for franking. *GHHF pays twice a year; its yield is an estimate from the last 12 months.
Asset allocation
By what each dollar is invested in or secured against, at cost, with the change in percentage points since 30 September. Buying GCI lifted residential mortgages by 3.3 points, and the KKC sale took corporate and other credit down by 4.1 points.
| Asset class | Weight at cost (change) |
|---|---|
| Equity income | |
| Listed investment companies (WHI, PL8, WMX) | 38.0% (+0.3) |
| Credit | |
| Residential mortgages (GCI) | 25.9% (+3.3) |
| Commercial property debt (MXT 58%, TCF, QRI) | 20.0% (−0.1) |
| Corporate and other credit (KKC, LEND, MA1, MXT 42%) | 15.4% (−4.1) |
| Total credit | 61.3% (−1.0) |
| Growth | |
| Geared diversified shares (GHHF) | 0.6% (+0.6) |
Comments
October distributions
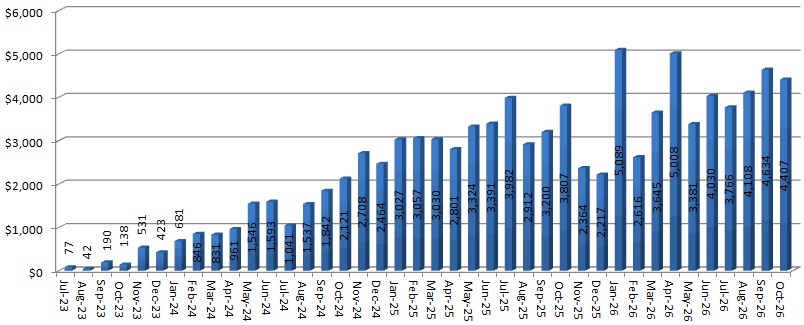
Distributions paid in October came to $3,938 in cash, plus $471 of franking credits on the LIC dividends: $4,408 gross.
The credit trusts paid $2,839 between 8 and 23 October. WHI, PL8 and WMX paid $1,098 on 30 October and carried all of the franking.
By cash, GCI was the largest single payer at $930, ahead of WHI at $828.
Each payment goes to the units held at the trust’s record date, so October’s figures reflect September’s holdings: 71,000 GCI units, for example, against the 89,000 held at month end.
Franked LICs, cash Franking, refunded at tax time Credit trusts and LEND, cash
| Paid | Holding | Units at record | Rate | Cash | Franking |
|---|---|---|---|---|---|
| 8 Oct | MXT | 50,000 | 1.30c | $650.00 | |
| 8 Oct | TCF | 7,500 | 5.00c | $375.00 | |
| 9 Oct | GCI | 71,000 | 1.31c | $930.10 | |
| 15 Oct | QRI | 21,000 | 1.006c | $211.26 | |
| 15 Oct | MA1 | 12,000 | 1.3366c | $160.39 | |
| 16 Oct | LEND | 1,000 | 14.0c | $140.00 | |
| 23 Oct | KKC | 22,300 | 1.67c | $372.41 | |
| 30 Oct | WHI | 142,000 | 0.583c | $827.86 | $354.80 |
| 30 Oct | PL8 | 30,000 | 0.55c | $165.00 | $70.71 |
| 30 Oct | WMX | 16,000 | 0.66c | $105.60 | $45.26 |
| October | $3,937.62 | $470.77 |
A sell-off in listed credit
The month opened with a sell-off in listed credit. Metrics’ three listed trusts were suspended on 28 September, after their auditor, KPMG, found valuation differences and the accounts ran late. The RBA lifted the cash rate to 4.60 per cent the next day, its fourth rise of the year, and property lenders fell across the market. TCF was still working through the August collapse of its largest borrower, the Bathla Group. MXT returned to trading on 5 October with audited accounts, a clean audit opinion and a 30 June net asset value of $1.9617. Through all of this the asset values reported by GCI, QRI and MA1 barely moved while their prices fell.
Distribution rates
Six of the seven credit holdings announced October rates at or above September’s.
MA1’s estimate rose 20.1 per cent, MXT returned to its August rate of 1.46c, and GCI and QRI each rose about 5 per cent. KKC and TCF held at 1.67c and 5.0c. LEND cut to 13.5c, its third reduction since June.
The October rates for GCI, MXT, TCF, QRI and MA1 are the trusts’ estimates; actual rates are confirmed in early November.
Among the LICs, WHI paid its base 0.583c (September’s 0.883c included a 0.300c half-yearly top-up) and has declared the same rate for November and December. PL8 paid 0.55c and has declared 0.55c for November. WMX paid 0.66c.
Changes to the portfolio
I bought GCI, WHI and TCF while prices were down, sold 8,515 KKC units and opened GHHF. GHHF is a geared, diversified share fund holding Australian, global and emerging market shares, and it starts the growth component. Net of the KKC sale, the cost base rose by $55,401.
| Holding | Units 30 Sep | Units 31 Oct | Change | Detail |
|---|---|---|---|---|
| GCI | 71,000 | 89,000 | +18,000 | Bought at about $1.98 on average. NTA at 30 Sep: $2.0052. |
| WHI | about 131,000 | 150,000 | about +19,000 | Bought at about $1.24 on average. |
| TCF | 7,500 | 9,650 | +2,150 | Bought at about $4.73 and $4.81. NAV at 30 Sep: $5.968. |
| KKC | 22,300 | 13,785 | −8,515 | Sold. |
| GHHF | 0 | 122 | +122 | New holding at $36.35. |
News from the holdings
- TCF. The September quarter update (22 October) reported 11 of 25 lots and houses on loans 1 and 2, and 5 townhouses on loan 4, under unconditional contract. TCF bought the senior loan on loan 3, putting in another $5.2m, and held $1.0m in cash on 12 October. It declared 5c for October.
- MXT. Back on the ASX from 5 October. Its NTA at 30 September was $1.9613 (14 October). IIR’s rating on MXT remains under review, and S&P’s CreditWatch on the underlying Metrics funds is still open.
- MA1. On 21 October the MA Secured Loan Series, about 18.5 per cent of MA1 through its underlying fund, suspended applications and redemptions from 31 October until at least 31 March 2027, citing a weaker residential market. MA1’s manager said it does not expect a material impact.
- QRI. The September report (26 October) moved two loans to one borrower, 2 per cent of the portfolio, into enforcement, the first in the 12 months its report covers. A controller is selling the security, and the manager expects repayment within about four months.
- LEND. October distribution cut to 13.5c (30 October), from 15.0c in June.
- WHI. Shareholders approved a placement of up to 120m shares on 16 October. It has not been priced. The annual report came out on 23 October.
Income from November
At October’s rates on month-end holdings, the portfolio earns $4,870 a month gross: $4,377 in cash and $492 in franking credits, 8.34 per cent a year on cost. The credit component yields 9.01 per cent on cost and the LICs 7.37 per cent.
| Holding | Units | Avg cost | Cost base | Weight | Rate (Oct) | Monthly gross | Yield on cost |
|---|---|---|---|---|---|---|---|
| WHI | 150,000 | 1.317 | $197,550.00 | 28.20% | 0.583c | $1,249 | 7.59% |
| GCI | 89,000 | 2.0416 | $181,702.40 | 25.94% | 1.386c | $1,234 | 8.15% |
| MXT | 50,000 | 1.9182 | $95,910.00 | 13.69% | 1.46c | $730 | 9.13% |
| TCF | 9,650 | 5.3556 | $51,681.54 | 7.38% | 5.00c | $483 | 11.20% |
| PL8 | 30,000 | 1.399 | $41,970.00 | 5.99% | 0.55c | $236 | 6.74% |
| QRI | 21,000 | 1.5454 | $32,453.40 | 4.63% | 1.0532c | $221 | 8.18% |
| KKC | 13,785 | 2.1157 | $29,164.92 | 4.16% | 1.67c | $230 | 9.47% |
| WMX | 16,000 | 1.6794 | $26,870.40 | 3.84% | 0.66c | $151 | 6.74% |
| MA1 | 12,000 | 1.9956 | $23,947.20 | 3.42% | 1.6056c | $193 | 9.65% |
| LEND | 1,000 | 14.7982 | $14,798.20 | 2.11% | 13.5c | $135 | 10.95% |
| GHHF | 122 | 36.35 | $4,434.70 | 0.63% | half-yearly* | $9 | 2.32% |
| Total | $700,482.76 | 100% | $4,870 | 8.34% |
| Component | Cost base | Weight | Monthly gross | Yield on cost |
|---|---|---|---|---|
| Equity income (WHI, PL8, WMX) | $266,390 | 38.03% | $1,636 | 7.37% |
| Credit (GCI, MXT, TCF, QRI, KKC, MA1, LEND) | $429,658 | 61.34% | $3,225 | 9.01% |
| Growth (GHHF) | $4,435 | 0.63% | $9 | 2.32% |
Monthly gross uses each trust’s October rate on 31 October holdings, with franking grossed up at 30%. *GHHF pays twice a year; the figure is its last 12 months (68.89c cash, 84.39c gross) spread monthly, an estimate.
Franked LICs, cash Franking Credit trusts and LEND, cash
Progress
| Measure | 30 Sep | 31 Oct | Change |
|---|---|---|---|
| Cost base | $645,082 | $700,483 | +$55,401 |
| Monthly gross income, month-end holdings at the latest declared rates | $4,319 | $4,870 | +$551 |
| Yield on cost, grossed up | 8.03% | 8.34% | +0.31 pts |
| Holdings | 10 | 11 | +1 |
Summary
October tested listed credit. The Metrics suspension and the fourth rate rise of the year arrived together, on top of Bathla’s collapse in August, and prices across the sector fell further than the assets behind them. The trusts kept paying. Every credit holding made its September distribution in October, and all but LEND declared October rates at or above September’s.
I bought GCI, WHI and TCF into the weakness, sold part of KKC and opened a small growth position in GHHF. Most of that buying came after September’s record dates, so October’s $4,408 gross understates what the portfolio now earns: about $4,870 a month at October’s rates.
Note for readers: all figures are at cost and before tax, and cash awaiting investment is not included. Distribution rates and dates come from each trust’s own ASX announcement, read on Market Index; estimates are marked. Payments are counted on the units held at each record date.
Disclaimer: this post describes my own portfolio and decisions for information only. It is not personal financial advice and does not take your circumstances into account.
Monthly dividends recieved since July 2023